Could a Seller Credit Help When the Mortgage Payment Feels Too High?
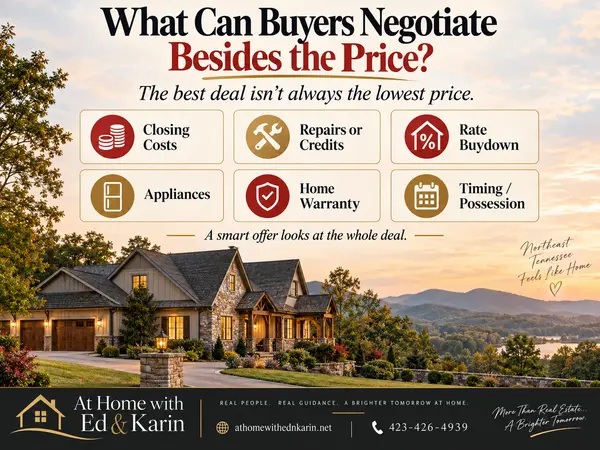
You find a Northeast Tennessee home that checks the boxes. Then you look at the estimated monthly payment and put the listing aside. Before you move on, it may be worth comparing a lower price with a seller contribution toward eligible financing costs.
A seller credit is money the seller agrees to contribute toward costs your loan program allows. What you can use it for depends on the financing and the agreement you negotiate. We spoke with Gregg Pechmann of CrossCountry Mortgage about a few ways buyers could compare their options.
If moving expenses are crowding your budget
Imagine you have enough set aside for closing, but moving and getting settled will stretch your savings. For a qualified buyer using an eligible FHA fixed-rate loan, Gregg’s ZMG Easy Move program may allow an approved seller or builder contribution toward some early mortgage interest. Ask Gregg which expenses you would still pay and when the assistance ends.
If the first year is the tightest
Imagine you can afford the regular payment and would welcome some breathing room as you settle in. A seller-funded 1-0 buydown could reduce your out-of-pocket principal and interest payment in the first year. From year two onward, you pay the full principal and interest amount at the fixed note rate.
If you’d prefer two steps up
A seller-funded 2-1 buydown could give you more relief in the first year and a smaller amount in the second. The full principal and interest payment begins in year three. When you compare options, look at the full housing cost after the subsidy ends, including taxes, homeowners insurance, any mortgage insurance, and applicable HOA dues.
Compare the same home both ways
Ask what a price reduction would do to the loan amount and monthly payment. Then compare it with a seller contribution, including the cash needed at closing, how long any payment relief lasts, and what you would pay afterward. Seller agreement, borrower qualification, property eligibility, and program limits all matter.
If you have a listing or even just a price range, reach out to Ed & Karin at Epique Realty. We can introduce you to Gregg so he can prepare a comparison based on the home and your situation. You’re welcome to compare his figures with those from a lender you already work with.
Categories
Recent Posts
GET MORE INFORMATION