Mortgage Rates Are High — But Here’s What You CAN Control
Mortgage Rates Are High — But Here’s What You CAN Control
If you’ve been thinking about buying a home, you’ve probably noticed the headlines:
Mortgage rates are back above 7%.
And yes—that matters.
A higher interest rate affects your monthly payment and how much home you may comfortably afford.
But here’s something we think buyers need to hear:
You Can’t Control Mortgage Rates. But You May Have More Control Over YOUR Rate Than You Think.
Mortgage rates move with the broader financial markets. None of us gets to decide where they’ll be next week, next month, or next year.
What you can do is focus on the things that may improve the financing options available to you.
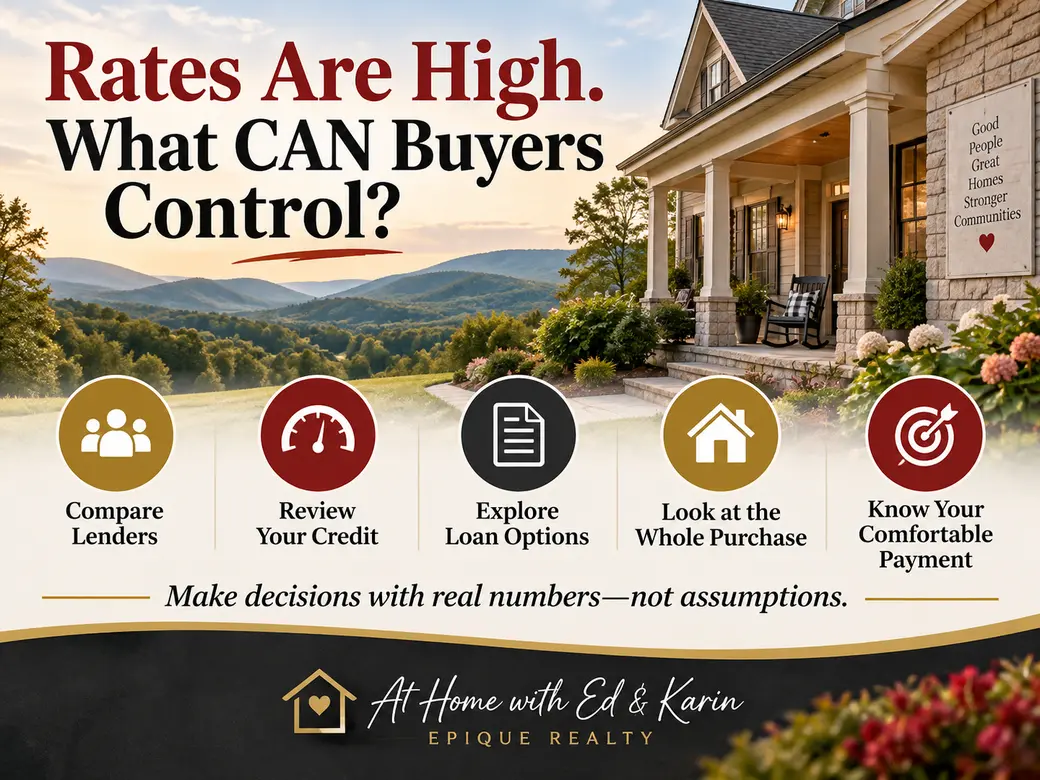
1. Shop More Than One Lender
Different lenders can offer different rates, fees, loan programs, and credits—even to the same borrower.
Don’t compare just the advertised interest rate.
Ask about:
-
Interest rate
-
APR
-
Closing costs and lender fees
-
Points
-
Lender credits
-
Estimated monthly payment
A slightly lower rate with much higher fees isn’t automatically the better deal.
2. Pay Attention to Your Credit
Your credit profile can affect the rate and loan options available to you.
That doesn’t mean you need perfect credit.
But before buying, it may make sense to review your credit, correct any errors, and talk with a lender about whether there are realistic steps that could improve your position.
And please don’t start closing accounts or making major financial changes without talking with your lender first!
3. Explore Different Loan Programs
Conventional isn’t the only option.
Depending on your qualifications, FHA, VA, USDA, and other programs may offer different combinations of down payment requirements, mortgage insurance, rates, and costs.
The “best” loan isn’t necessarily the same for every buyer.
4. Ask About Points and Rate Buydowns
Some buyers may choose to pay money upfront—often called discount points—to obtain a lower interest rate.
Depending on the transaction, there may also be opportunities to negotiate seller contributions toward allowable costs.
But this is where we want to compare the numbers carefully.
How much does it cost to lower the rate?
How much does that save each month?
How long would you need to own the home before the upfront cost pays for itself?
Those are much better questions than simply asking, “Can I get a lower rate?”
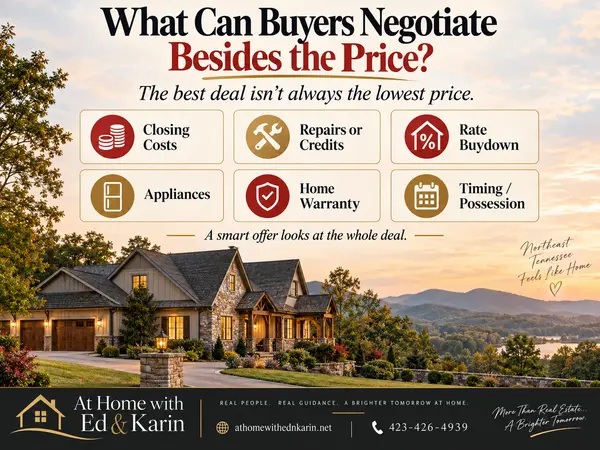
5. Remember: The House Is Negotiable Too
Interest rate is only one piece of affordability.
In the right situation, we may be able to negotiate:
-
Purchase price
-
Seller-paid allowable closing costs
-
Repairs or credits
-
Other terms that reduce the amount of cash you need
A lower rate is valuable—but so is buying the right house at the right price.
Should You Wait for Rates to Fall?
Maybe.
For some buyers, waiting is absolutely the right decision.
But none of us knows exactly when rates will fall—or what home prices and buyer competition will look like when they do.
Instead of trying to perfectly time the mortgage market, we encourage buyers to ask:
“Can I comfortably afford the right home under TODAY’S numbers?”
If the answer is no, waiting may make sense.
If the answer is yes, then we can look at the complete picture and decide whether buying now fits your goals.
The Bottom Line
You can’t control the national mortgage market.
But you can control how prepared you are, how many options you compare, the home you choose, and how we structure your offer.
So don't let one headline mortgage rate automatically make the decision for you.
Find out what YOUR numbers actually look like.
Karin and I are happy to help you get started and connect you with lenders who can walk you through the financing side.
No pressure. No predictions. Just good information so you can make the decision that’s right for you.
🎓 Our FREE Homebuyers Success Academy can also help you understand the buying process:
https://www.youtube.com/playlist?list=PLU-DcNzz_A94
Ed & Karin
At Home with Ed & Karin
Epique Realty
With HEART and a bit of HUMOR, you will feel At Home with Ed & Karin.
Mortgage rates and loan terms vary by lender, borrower qualifications, loan program, market conditions, and other factors. Consult a qualified mortgage professional regarding your individual situation.
Categories
Recent Posts
GET MORE INFORMATION